

Comparing the short-term volatility of the housing market with a long-term perspective.
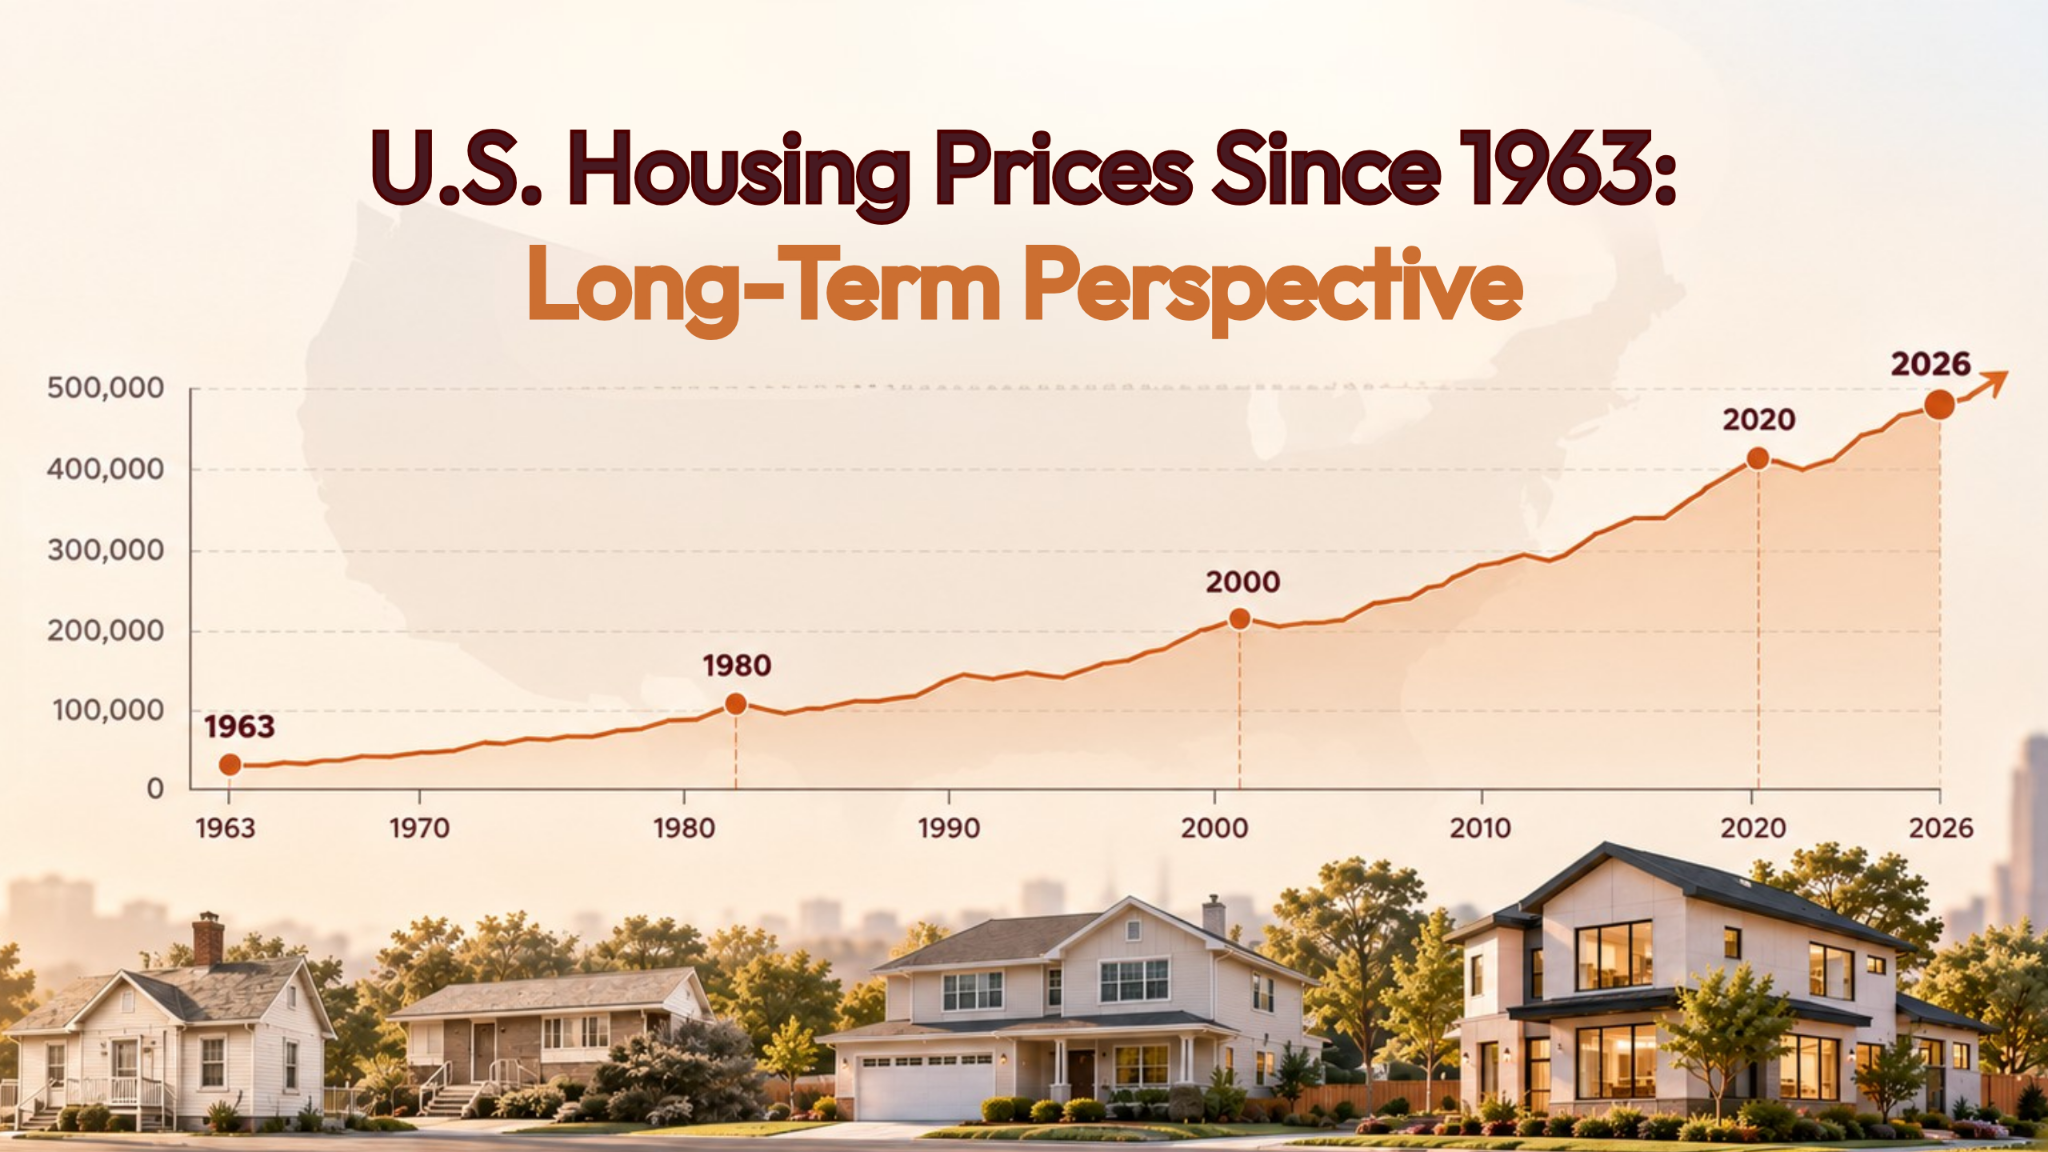
Housing markets change constantly. Mortgage rates rise and fall, construction activity shifts, and economic conditions affect both buyers and sellers. Looking beyond short-term headlines and examining decades of housing data can provide useful context for understanding how home prices have changed over time.
One long-running measure comes from the U.S. Census Bureau and U.S. Department of Housing and Urban Development (HUD) Median Sales Price of New Houses Sold for the United States, which illustrates the median price of newly constructed homes sold nationwide (1963-2026).
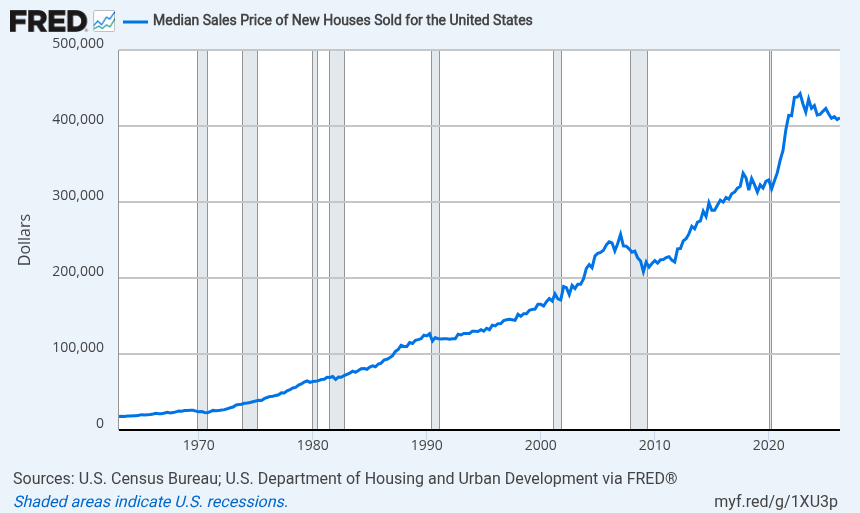
The data illustrate substantial long-term increases in new-home prices, along with periods when prices declined or remained relatively flat. Importantly, historical price changes do not predict what will happen to a particular property or real estate investment in the future.
The U.S. Census Bureau and HUD data includes information about new homes sold in the United States on a quarterly, not seasonally adjusted basis. It does not measure existing-home prices, rental income, operating expenses, transaction costs, financing costs, or an investor's total return.
That distinction is important when using historical housing data to evaluate real estate as an investment.
The historical data show that the median sales price of newly constructed homes in the United States has increased substantially since 1963. More recently, however, the data also demonstrate that housing prices do not move upward continuously.
Quarterly data show additional variation. The median price was $412,300 in Q4 2025, $408,500 in Q1 2026, and $410,700 in Q2 2026.
These movements illustrate an important feature of housing markets: a long-term upward historical trend can coexist with periods of declining, flat, or uneven prices.
Home prices can be influenced by many variables, including mortgage rates, household income, housing supply, construction costs, population trends, employment conditions, consumer demand, and broader economic activity.
The composition of homes sold also matters. Because the median represents the midpoint of homes sold during a particular period, changes in the types, sizes, locations, and price ranges of new homes being purchased can affect the reported median.
For that reason, a change in the national median sales price does not necessarily mean that every home in the country changed in value by the same percentage.
National housing statistics can provide useful historical context, but real estate is fundamentally local.
Property values may behave differently depending on location, property type, neighborhood conditions, local employment, housing inventory, taxes, insurance costs, maintenance needs, rental demand, and numerous other factors.
An individual property could appreciate, remain relatively unchanged in value, or decline even during a period when national housing measures are rising. Likewise, historical national price growth should not be treated as a forecast for a specific property's future value.
Price Appreciation Is Only One Part of Real Estate Investing
Changes in property value are one potential component of real estate investment performance, but they are not the only consideration.
For income-producing residential real estate, investors may also evaluate rental income, vacancies, maintenance expenses, property taxes, insurance, management costs, reserves, transaction costs, and other property-level expenses.
These factors can materially affect investment results. A property that increases in value does not necessarily produce a positive investment return after expenses, and rental income or distributions are not guaranteed.
Decades of U.S. housing data provide evidence that new-home prices have increased substantially over the long term, but the same history also includes periods of declining and uneven prices.
The appropriate takeaway is not that real estate will necessarily appreciate or that a particular time is favorable for investing. Instead, historical data can help investors place current market conditions within a broader context.
Investors evaluating real estate may want to consider both long-term market information and property-specific factors rather than relying on short-term price movements or national averages alone.
Past housing price trends do not predict future property values or investment results.
Fractional real estate investing provides another way to gain exposure to individual real estate assets without purchasing an entire property.
Through Realbricks, investors purchase ownership interests in an entity that owns the underlying property. Realbricks provides access to SEC-qualified fractional real estate offerings and educational resources designed to help investors understand individual properties and how fractional real estate investing works.
Interested in building your own real estate portfolio? Investors can explore available properties and open an account on the Realbricks app or at Realbricks.com. Investors should review the information provided for each offering and consider whether the investment structure, risks, and potential outcomes are consistent with their own financial situation and investment objectives.
Create an account to get started. Minimum investments start at $100.
This article is for informational and educational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any securities. Real estate investments involve a high degree of risk and may result in the loss of some or all of your investment. Past performance is not indicative of future results. Market data provided is sourced from the Case-Shiller Index and other third-party reports believed to be reliable, but its accuracy and future projections are not guaranteed. Please consult with a financial advisor before making any investment decisions.
Be the first to know about property launches, portfolio updates, and announcements by subscribing to our newsletter.


Terra Mint Group, Corp ("Terra Mint"), as the Managing Member of Neptune REM, LLC ("Neptune") operates the RealBricks.com website (the "Site") and is not a broker-dealer or investment advisor. All securities related activity is conducted through Dalmore Group LLC, a registered broker-dealer and member of FINRA/SIPC, located at 525 Green Pl. Woodmere, NY 11598. You can review the brokercheck for Dalmore. An up-to-date Dalmore Form CRS is available.
You should speak with your financial advisor, accountant and/or attorney when evaluating any offering. Neither Terra Mint, Neptune, nor Dalmore makes any recommendations or provides advice about investments, and no communication, through this website or in any other medium, should be construed as a recommendation for any security offered on or off this investment platform. The Site may make forward-looking statements. You should not rely on these statements but should carefully evaluate the offering materials in assessing any investment opportunity, including the complete set of risk factors that are provided as part of the offering circular for your consideration.
Neptune is conducting public offerings pursuant to Regulation A, as amended, through the Site. The most current offering circular for Neptune is available here. Past performance is no guarantee of future results. Investments such as those on the Realbricks platform are speculative and involve substantial risks to consider before investing. These risks are outlined in the respective offering materials and including, but not limited to, illiquidity and a complete loss of capital. Key risks include, but are not limited to, limited operating history, reliance on key personnel, inherent risks in investing in real estate, distributions may not be received on predictable schedule and or at all by Investors, and lack of voting rights. Also, the adverse economic effects of the COVID-19 pandemic remain unknown and could materially impact this investment. An investment in an offering constitutes only an investment in a particular series and not in the underlying asset(s). Investors should carefully review the risks located in the respective offering materials for a more comprehensive discussion of risk.
From time to time, Neptune may undertake "testing the waters" for additional series of securities to be offered pursuant to Regulation A. For offerings that have not yet been qualified, no money or other consideration is being solicited, and if sent in response, will not be accepted.
NO MONEY OR OTHER CONSIDERATION IS BEING SOLICITED, AND IF SENT IN RESPONSE, WILL NOT BE ACCEPTED.
NO OFFER TO BUY THE SECURITIES CAN BE ACCEPTED AND NO PART OF THE PURCHASE PRICE CAN BE RECEIVED UNTIL THE OFFERING STATEMENT FILED BY THE COMPANY WITH THE SEC HAS BEEN QUALIFIED BY THE SEC. ANY SUCH OFFER MAY BE WITHDRAWN OR REVOKED, WITHOUT OBLIGATION OR COMMITMENT OF ANY KIND, AT ANY TIME BEFORE NOTICE OF ACCEPTANCE GIVEN AFTER THE DATE OF QUALIFICATION.
AN INDICATION OF INTEREST INVOLVES NO OBLIGATION OR COMMITMENT OF ANY KIND.
AN OFFERING STATEMENT REGARDING THIS OFFERING HAS BEEN FILED WITH THE SEC. YOU MAY OBTAIN A COPY OF THE PRELIMINARY OFFERING CIRCULAR THAT IS PART OF THAT OFFERING STATEMENT FROM: Neptune REM, LLC 412 W Norfolk Ave STE 2, Norfolk, NE 68701 OR HERE.
Investment overviews contained herein contain summaries of the purpose and the principal business terms of the investment opportunities. Such summaries are intended for informational purposes only and do not purport to be complete, and each is qualified in its entirety by reference to the more-detailed discussions contained in the respective offering circular filed with the SEC.
Realbricks does not offer refunds after an investment has been made. Please review the relevant offering materials and subscription documentation for more information.
Potential investors should not rely on any forward-looking statements regarding any investment opportunity, which is based on our beliefs and information currently available to us. The words “anticipate,” “believe,” “expect,” “aim,” “potential,” “design,” “target,” “intend,” “may,” “might,” “plan,” “estimate,” “project,” “projection,” “should,” “will,” “would,” “result” and similar expressions identify forward-looking statements. Such statements are subject to risks, uncertainties, and assumptions and are not guarantees of future performance, which may be affected by known and unknown risks, trends, uncertainties, and factors that are beyond our control. These risks could result in the loss of your investment. See the offering materials for detailed information.
Neptune does not have a public trading market for its Series Interests. While it intends to seek a quotation on PPEX, an alternative trading system (ATS) operated by North Capital Investment Technology, Inc. (“PPEX”) with a view to providing our holders of Series Interests with potential liquidity in the form of a secondary market for their investment in our Series Interests. However, there can be no guarantee that a secondary market may develop, or if it does, as to the volume or pricing with respect to any secondary trading that might develop. The PPEX does not employ market makers to provide liquidity, unlike national securities exchanges. Until Neptune’s Series Interests are listed, if ever, you may not sell the company’s Series Interests. Therefore, it may be difficult for you to sell Neptune’s Series Interests at the time you wish to do so, if you are able to sell them at all. If you are able to sell your Series Interests, you may have to sell them at a substantial discount to their public offering price. Because of the illiquid nature of our Series Interests, you should purchase Neptune’s Series Interests only as a long-term investment and be prepared to hold them for an indefinite period of time.
Property information shown has been provided from various sources, which can include the seller and/or public records. It is believed reliable but not guaranteed and should not be relied upon without independent verification.
Disclaimer: Images, Information and Floor Plan and Measurements are approximate and are for illustrative purposes only. We make no guarantee, warranty or representation as to the accuracy and completeness of the floor plans, measurements and or any information provided. You or your advisers should conduct a careful, independent investigation of the property to determine to your satisfaction as to the suitability of the property for your space requirements. All pricing and availability is subject to change. The information is to be used as a point of reference and not a binding agreement.


